


I am sending out a short note building on yesterday’s report. It launches a new regime model that maps HOW MUCH interest rate risk exists in the system, which is critical for understanding WHERE the directional skew of interest rates sits.

This model quantifies the interest rate regimes that matter for managing interest rate risk. The three panels represent the three angles from which to systematically analyze that risk: interest rate volatility, positioning, and directional skew. When all three align in the same direction, large moves in rates always occur.
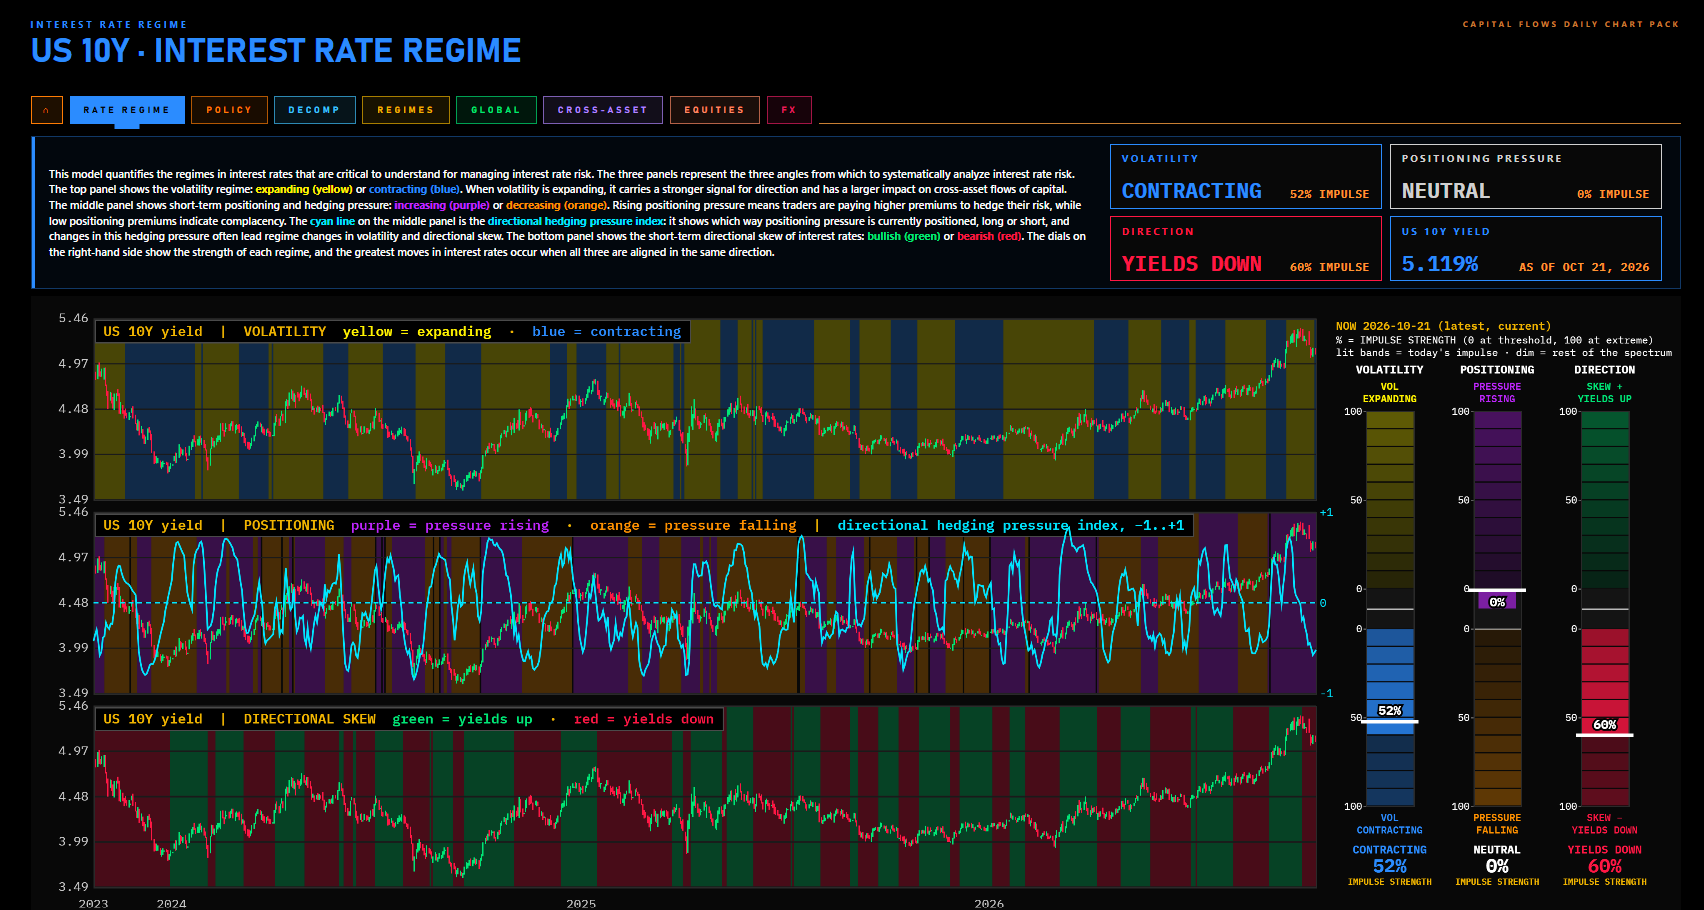
This model will be updated and sent out daily to paid subscribers. The full PDF is below, along with a short analysis of how this frames positioning into FOMC.